

 0800 855 888
Bike Finance: Essential Steps for Smart Borrowing
Introduction
Navigating the world of bike finance can feel overwhelming, especially with so many options available to potential buyers. But don’t worry! Understanding the key concepts and terminology associated with motorcycle and bicycle loans is crucial for making informed financial decisions. As you seek to acquire your dream ride, the challenge lies in figuring out which financing route will best suit your needs and budget.
So, what steps can you take to ensure smart borrowing and secure the most favourable terms in a competitive market? By exploring the features of various lending options, you can uncover their advantages and the benefits they offer for your financial health. Remember, you can take control of your finances! Every step counts, and with the right information, you can confidently navigate this journey.
Define Bike Finance: Key Concepts and Terminology
Bike finance provides various financial products that enable you to buy a motorcycle or bicycle without having to pay the entire amount upfront. Understanding key terms can empower you to make informed financial decisions.
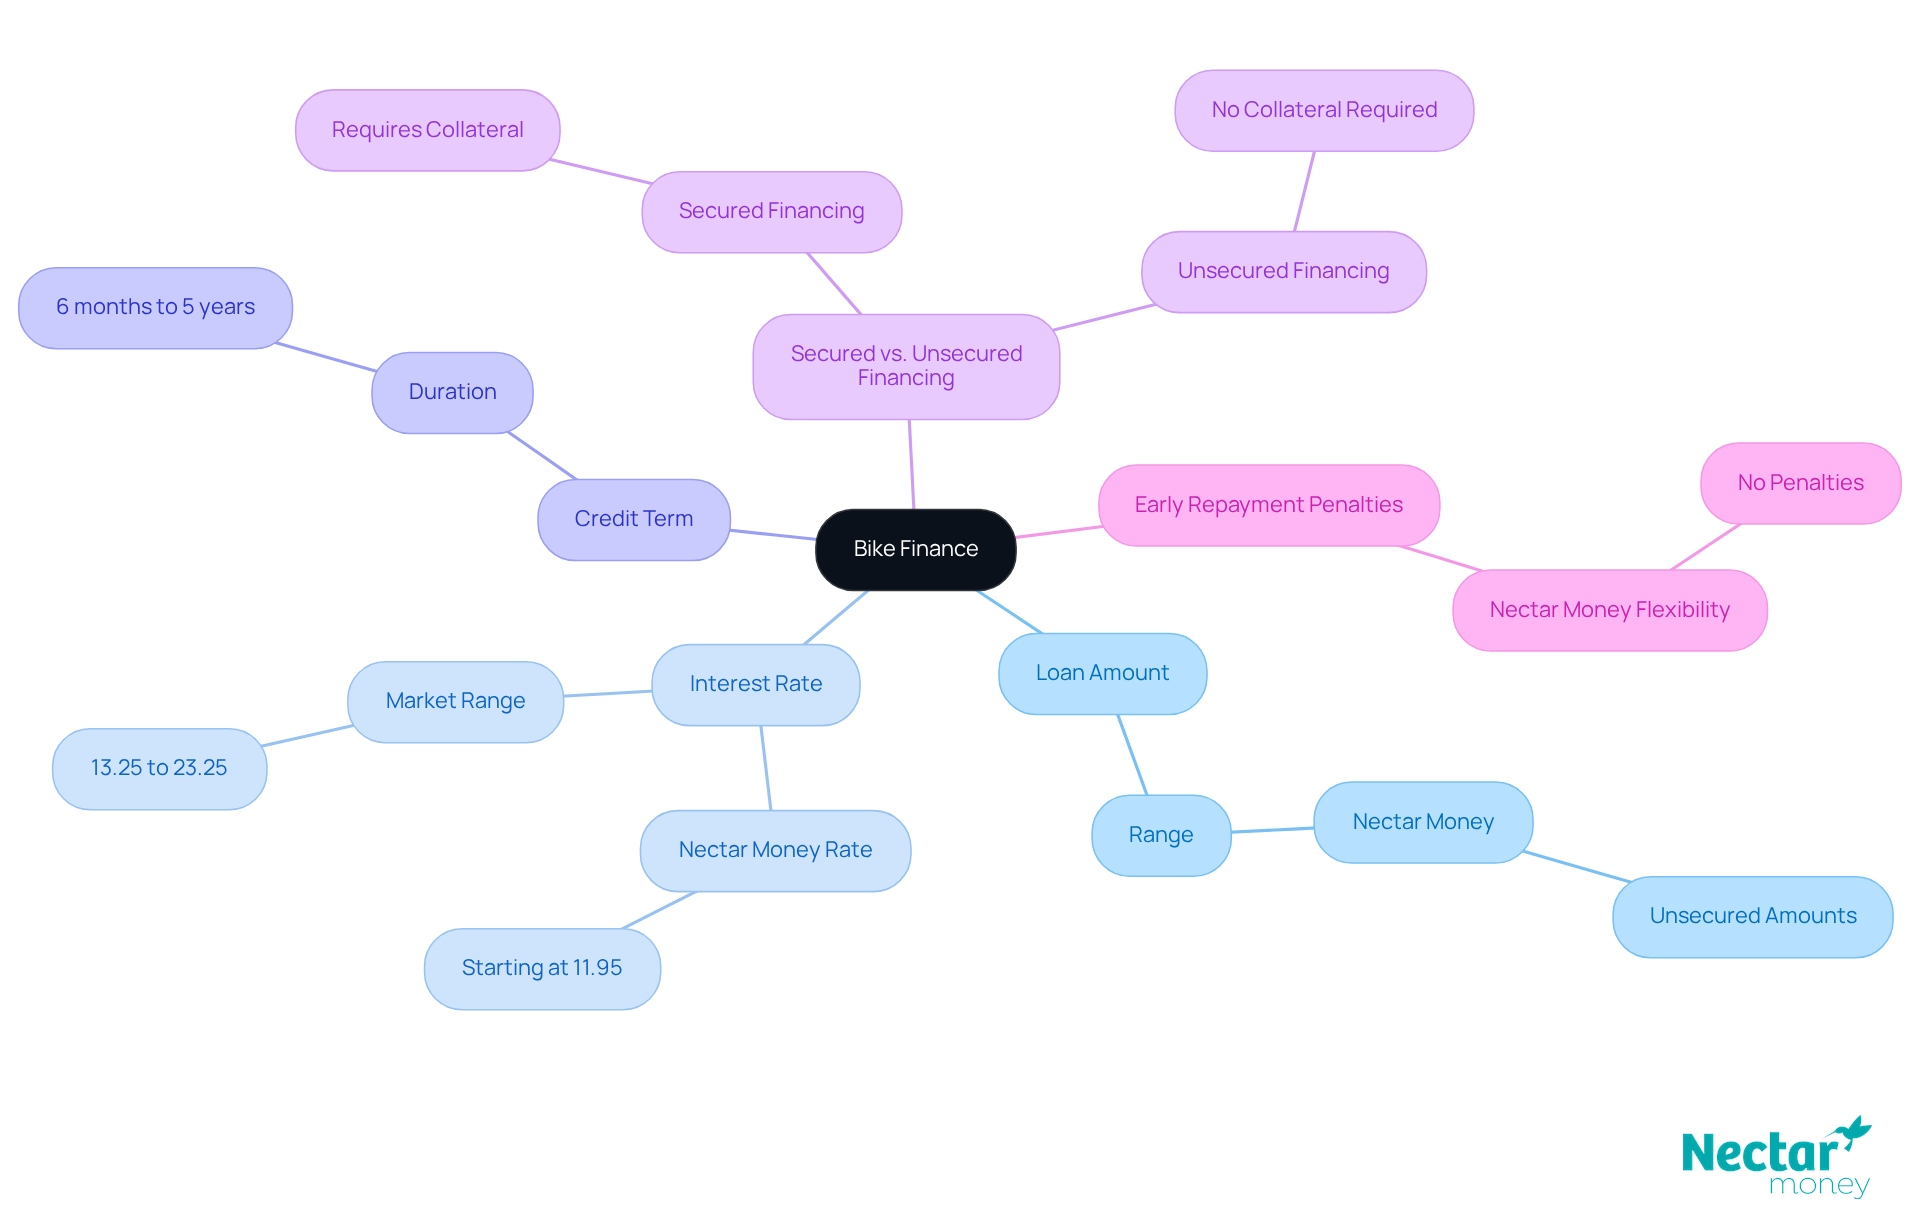
With Nectar Money, you can borrow unsecured amounts from $2,000 to $40,000. This flexibility allows you to choose a bike finance option that perfectly fits your financial needs. The interest rate represents the cost of borrowing, shown as a percentage of the amount borrowed. For Nectar Money, rates start at 7.95%% annually. Keep in mind that unsecured financing rates among lenders for motorcycle financing in New Zealand can range from 13.25% to 23.25% annually as of 2026. The loan term is the duration over which you repay the loan, typically between 6 months and 5 years. You can choose a term that aligns with your budget, making it easier to manage your finances. Secured options require collateral, like the bicycle itself, while unsecured alternatives, such as those offered by Nectar Money, do not. This distinction can significantly influence your borrowing approach. Early repayment fees are charges that may apply if you pay off your debt early. Fortunately, in bike finance, many lenders avoid imposing these penalties.
By grasping these terms, you can take control of your finances! For instance, using a loan calculator can help you estimate your repayments based on your chosen amount and term, ensuring transparency in costs. Additionally, remember to factor in the establishment fee of $240 and the admin fee of $1.75 per repayment when evaluating the total cost of financing.
As monetary expert Phil West wisely notes, “Cash provides the best leverage for negotiating with the widest variety of sellers.” This highlights the importance of financial preparedness. With the right steps, you can confidently navigate the bike finance landscape!
Explore Financing Options: Loans, Payment Plans, and More
When exploring bike finance, you have several options tailored to meet different needs and financial situations:
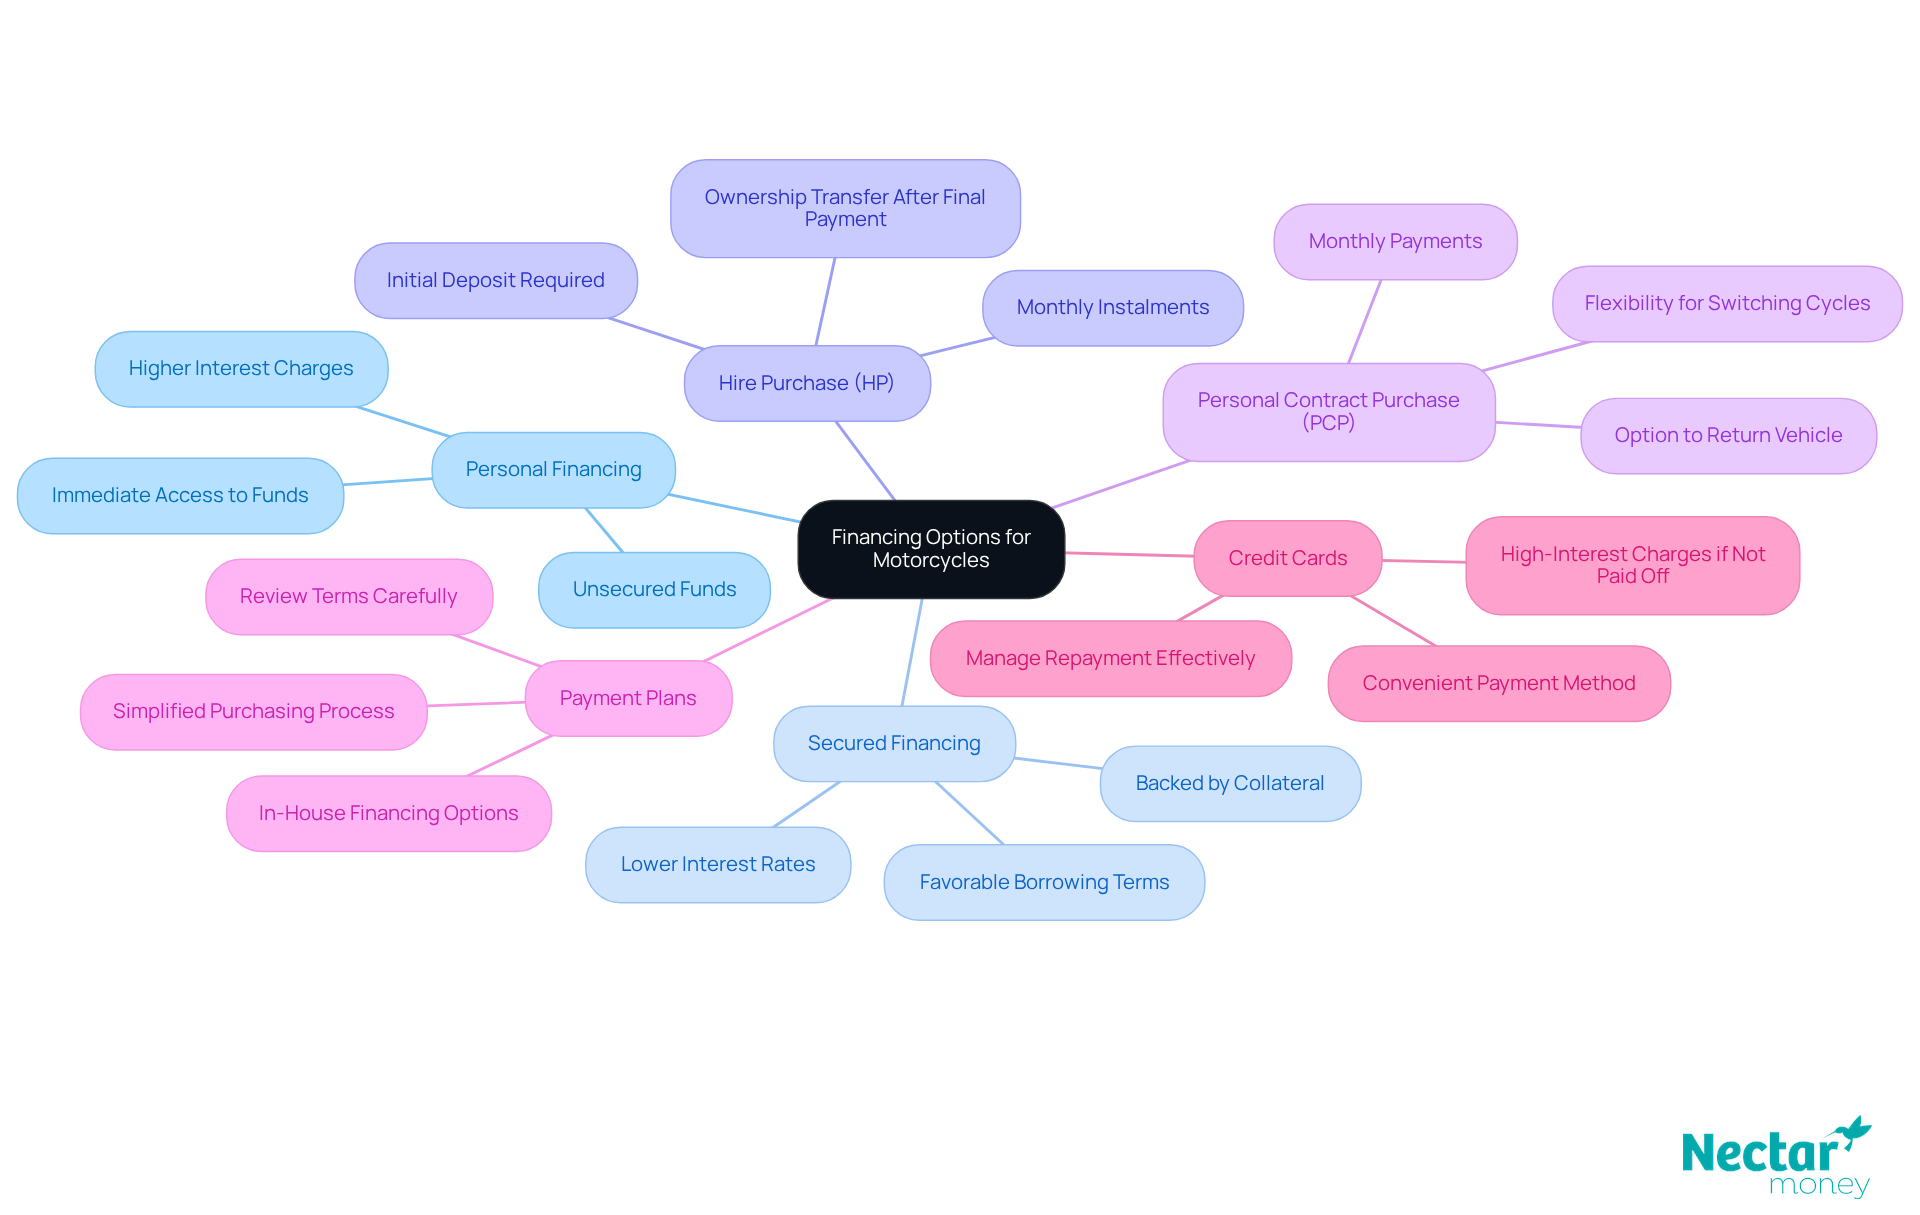
- Personal Loans: These unsecured funds can be used for any purpose, including purchasing a motorcycle. While they offer flexibility, keep in mind that they usually come with higher interest rates, making them a more expensive choice in the long run. However, if you need immediate access to funds, this could be a viable option.
- Secured Loans: Backed by collateral, such as the motorcycle itself, secured loans typically offers lower interest rates. This reduced risk for lenders can lead to more favourable borrowing terms, making it an attractive choice for many buyers. Financial advisors often recommend bike finance for motorcycle purchases because of its affordability and lower monthly payments, which help you manage your budget effectively.
- Hire Purchase: This secured loan option requires an initial deposit followed by monthly instalments. Ownership of the bicycle transfers to you after the final payment, allowing for a structured payment plan that fits within your budget. With HP, you can enjoy your bike while gradually paying it off, making it a practical choice.
- Personal Contract Purchase: Similar to HP, PCP allows you to make monthly payments with the option to return the vehicle at the end of the term instead of buying it outright. This flexibility can be appealing for those who like to switch cycles frequently, giving you the freedom to choose what works best for you.
- Retailer Financing: Some retailers offer in-house financing options, enabling you to pay in instalments directly to the seller. This can simplify the purchasing process, but be sure to review the terms carefully to avoid high-interest rates. Taking this route can make your bike purchase more manageable.
- Credit Cards: While using a credit card for a bike purchase can be convenient, it may lead to debt if the balance isn’t paid off quickly. It’s wise to consider this option only if you can manage the repayment effectively. If you can pay it off promptly, this could be a straightforward way to finance your bike.
Each funding method, such as bike finance, has its benefits and drawbacks, so it’s essential to assess your financial situation and preferences before making a choice. As you consider your options, remember that as of 2026, interest rates range from 9.95% to 23.00%, reflecting the competitive landscape of motorcycle financing. Discussing with a financial advisor can provide valuable insights tailored to your unique situation, ensuring you select the best choice for your bike purchase. You can take control of your finances and make an informed decision!
Apply for Bike Finance: Steps to Secure Your Loan
Securing bike finance may seem daunting, but by taking the right steps, you can gain control of your finances and ensure a smooth application process. Here’s how:
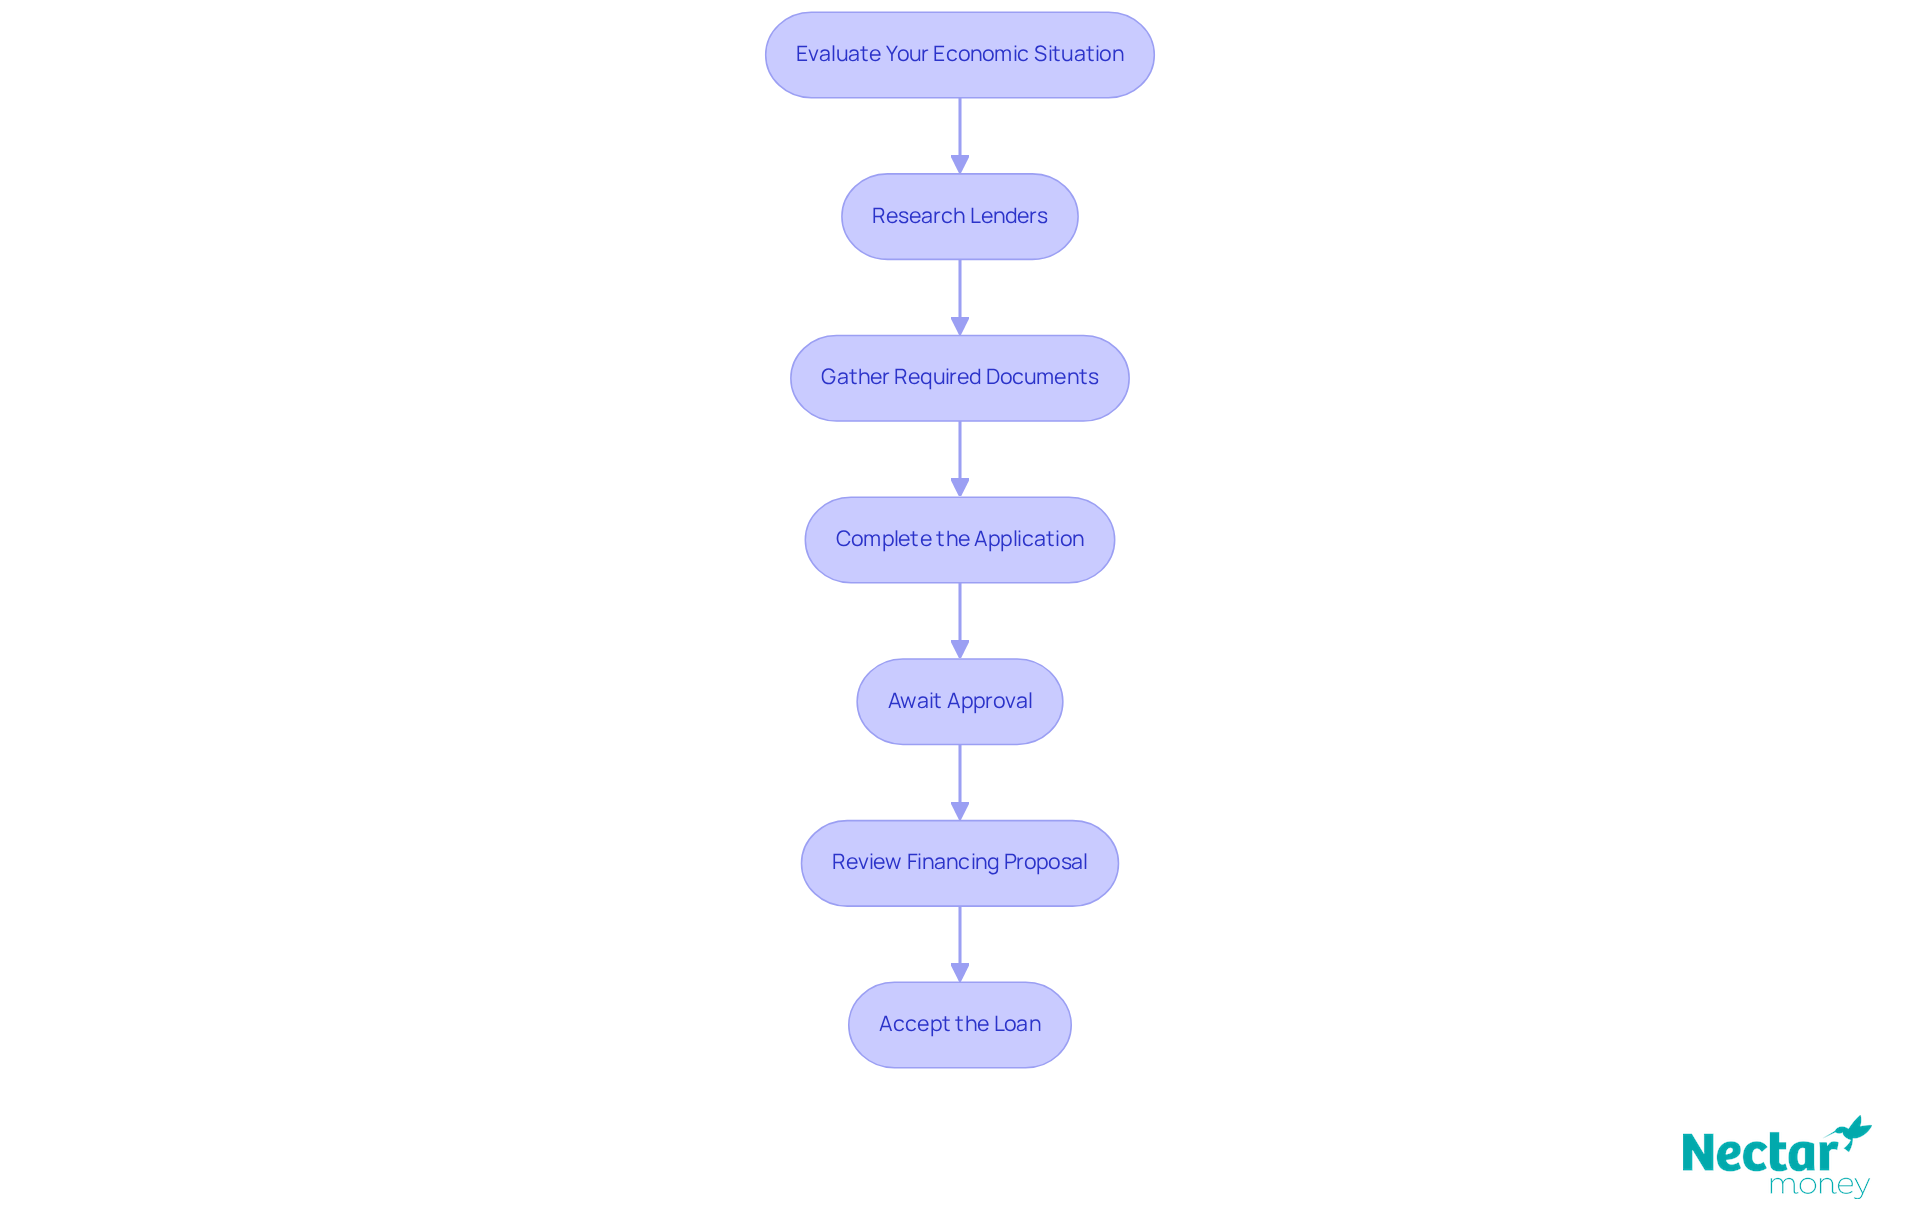
- Start by assessing your monetary health. Determine how much you can afford to borrow and repay monthly by considering your income, expenses, and any existing debts. This self-assessment is crucial for your budget and sets a solid foundation for your financial journey.
- Explore various lenders, including Nectar Money, to identify the most competitive rates and favourable terms. Pay attention to customer reviews and feedback to gauge the reliability of each lender. Finding the right lender can make a significant difference in your financing experience.
- Prepare the necessary documentation for your application. This usually consists of proof of income, identification, and details of any existing financial commitments. Having these documents ready can expedite the application process, making it easier for you to move forward.
- Fill out the lender’s application form accurately. Providing precise information is vital to avoid delays in processing your application. Remember, every detail counts in this process!
- Await Approval: After submission, lenders will review your application and may conduct credit checks. This review process can take anywhere from a few minutes to several days, depending on the lender’s procedures. Stay positive during this waiting period; you’re one step closer to your goal!
- If your application is approved, carefully examine the terms of the financing. Pay close attention to interest rates, repayment schedules, and any associated fees to ensure they align with your financial goals. This is your opportunity to make sure the financing works for you.
- Once you are satisfied with the terms, sign the agreement to finalise the loan. Many lenders, including Nectar Money, offer quick disbursement options, allowing you to access your funds quickly. This means you can start enjoying your new bike sooner!
By following these steps, you can improve your chances of obtaining the best bike finance for your bicycle while ensuring that your financial situation stays manageable. Remember, every step counts, and you’re on the right path!
Evaluate Pros and Cons: Weighing Your Financing Choices
When considering bike finance, it’s essential to evaluate the pros and cons of each option to make an informed choice:
Pros:
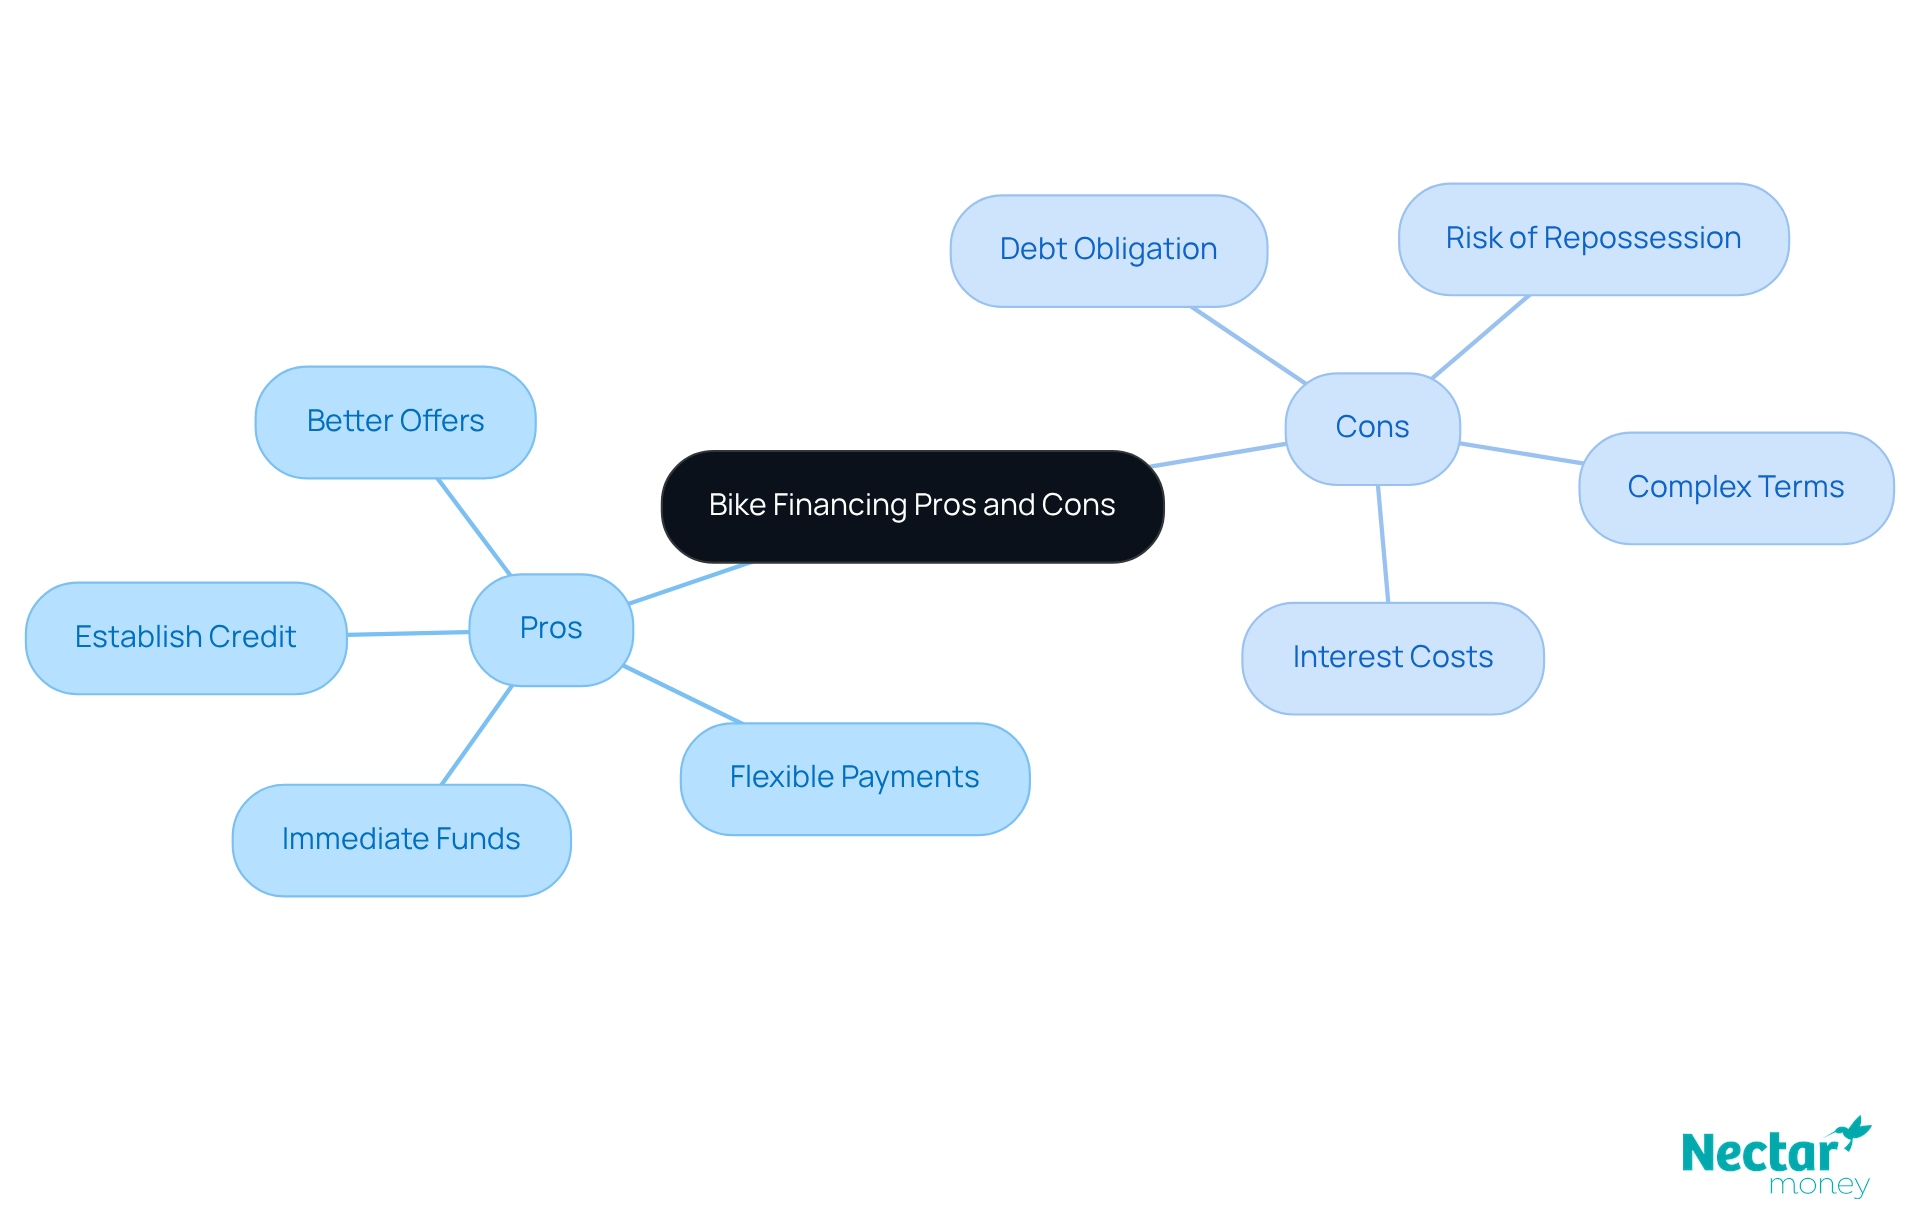
- Financing allows you to get your dream bike without having to save the entire amount upfront. This means you can quickly access the model you desire. With financing options, you can cover significant expenses, including bike purchases, without delay.
- Many lenders, including banks, offer customizable repayment plans. This flexibility lets you tailor your payments to fit your budget and financial situation, making it easier to manage your finances.
- By making timely repayments, you can improve your credit score. This can open doors to easier access to future financing and more favourable terms, which is especially beneficial if you plan to consolidate debts later on.
- Some financing options come with promotional terms or incentives, making it financially advantageous to finance rather than pay in full. A lender’s attractive terms on bike finance can help you secure a better deal.
Cons:
- Remember, borrowing money comes with interest, which can significantly increase the total cost of your bike over time. For example, the effective credit card rate was 10.1% in November 2023, highlighting the potential costs associated with financing.
- Financing means committing to monthly payments, which can strain your budget if not managed properly. Thankfully, a financial organization is dedicated to financial literacy, helping you understand and manage these obligations effectively.
- With secured credit, failing to meet repayment obligations can lead to losing your motorcycle. It’s crucial to stay on top of your payments to avoid this risk.
- Understanding the fine print of loan agreements can be tricky, potentially leading to unexpected costs or unfavourable conditions. Take the time to read and comprehend the terms before committing.
By carefully weighing these pros and cons, you can take control of your finances and make a decision that aligns with your financial goals. Every step counts!
Conclusion
Mastering bike finance can feel overwhelming, but understanding key concepts and making informed decisions tailored to your financial situation is entirely achievable. By familiarising yourself with essential terminology, financing options, and the application process, you can confidently navigate the complexities of borrowing.
Throughout this article, we’ve shared critical insights that can empower you. Evaluating your personal finances, exploring various lending options, and weighing the pros and cons of each financing method are all essential steps. Whether you choose secured loans, hire purchase, or in-house payment plans, grasping the terms and potential costs associated with each choice is vital. Moreover, the steps for applying for bike finance – from assessing your economic health to reviewing financing proposals – offer a clear roadmap for prospective borrowers like you.
Ultimately, making informed choices in bike financing can lead to greater financial control and satisfaction. By taking the time to evaluate your options and understand the implications of borrowing, you can secure the best possible financing for your needs. Embracing this knowledge not only empowers you to make smart borrowing decisions but also sets the stage for future financial success in the realm of bike ownership. Remember, every step counts, and you have the power to take control of your finances!
Frequently Asked Questions
What is bike finance?
Bike finance provides various financial products that allow you to purchase a motorcycle or bicycle without paying the entire amount upfront.
What is the loan amount range offered by Nectar Money for bike finance?
Nectar Money allows you to borrow unsecured amounts ranging from $2,000 to $40,000.
What is the interest rate for bike finance through Nectar Money?
The interest rates for Nectar Money start at 7.95%% annually. Unsecured financing rates for motorcycle financing in New Zealand can range from 13.25% to 23.25% annually as of 2026.
What is a credit term in bike finance?
The credit term is the duration over which you repay the loan, typically ranging from 6 months to 5 years.
What is the difference between secured and unsecured financing?
Secured financing requires collateral, such as the bicycle itself, while unsecured financing, like that offered by Nectar Money, does not require collateral.
Are there early repayment penalties with Nectar Money bike finance?
No, Nectar Money products offer greater flexibility by not imposing early repayment penalties.
What additional costs should I consider when financing a bike?
When evaluating the total cost of financing, you should factor in an establishment fee of $240 and an admin fee of $1.75 per repayment.
How can I estimate my repayments for bike finance?
You can use Nectar Money’s loan repayment calculator to estimate your repayments based on your chosen loan amount and term.
List of Sources
- Define Bike Finance: Key Concepts and Terminology
- Buying a bike on finance: everything you need to know | BikeRadar (https://bikeradar.com/advice/buyers-guides/bike-finance-guide)
- nectar.co.nz (https://nectar.co.nz/10-essential-tips-for-motorcycle-finance-in-nz-you-need-to-know)
- bennetts.co.uk (https://bennetts.co.uk/bikesocial/news-and-views/advice/buying-and-selling-a-bike/motorcycle-finance-explained)
- Bike Finance Explained | Autotrader (https://autotrader.co.uk/bikes/content/bike-finance-explained)
- Explore Financing Options: Loans, Payment Plans, and More
- kiwicarloans.co.nz (https://kiwicarloans.co.nz/motorbike-finance)
- What is the difference between personal loan and bike loan? (https://quora.com/What-is-the-difference-between-personal-loan-and-bike-loan)
- Lending and monetary statistics (https://rbnz.govt.nz/statistics/series/lending-and-monetary)
- Using Lombard loan to help an expat build their dream home abroad – Nedbank Private Wealth (https://nedbankprivatewealth.com/case_studies/using-lombard-loan-to-help-an-expat-build-their-dream-home-abroad)
- How does finance work on a motorcycle (https://motodealers.co.uk/riders-article/how-does-finance-work-on-a-motorcycle)
- Apply for Bike Finance: Steps to Secure Your Loan
- New Zealand: currently licensed motorbikes by licensing period 2024| Statista (https://statista.com/statistics/735203/new-zealand-currently-licensed-motorbikes-by-licensing-period?srsltid=AfmBOorQQ5fiRXzH7lCHo_NcnqmKcBnjYPO21uDHLRGnW2DSAYfuq_nn)
- Using Lombard loan to help an expat build their dream home abroad – Nedbank Private Wealth (https://nedbankprivatewealth.com/case_studies/using-lombard-loan-to-help-an-expat-build-their-dream-home-abroad)
- Evaluate Pros and Cons: Weighing Your Financing Choices
- Buying a bike on finance: everything you need to know | BikeRadar (https://bikeradar.com/advice/buyers-guides/bike-finance-guide)
- deliberatedirections.com (https://deliberatedirections.com/financial-strategy-quotes-business-leaders)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- 115 Best Motivational Quotes About Finance [2026] (https://acecloudhosting.com/blog/motivational-finance-quotes)
- Retail interest rates on lending and deposits (B3) (https://rbnz.govt.nz/statistics/series/exchange-and-interest-rates/retail-interest-rates-on-lending-and-deposits)
* Nectar Money offers competitive unsecured personal loan rates with fixed interest rates from 7.95% to 29.95% p.a., based on your credit profile. A $230 establishment fee and $1.75 administration fee per repayment apply. Strong Credit borrowers may qualify for low, competitive rates from 7.95% to 11.95% p.a.; Good Credit borrowers may qualify for rates from 14.95% to 22.95% p.a.; and Fair or Developing Credit borrowers may qualify for rates from 24.95% to 29.95% p.a. The broad range helps Nectar offer low interest rates to borrowers with excellent credit, while also providing loan options for more New Zealanders, including borrowers with fair or developing credit profiles. Learn more here.
All loans are subject to responsible lending checks and standard borrowing criteria. Please see our privacy policy and rates and terms, or visit our FAQs for the most up to date information. This publication is provided for general information purposes only and does not constitute legal, tax, financial, or other professional advice from Nectar Money. It is not intended as a substitute for obtaining advice from a financial adviser or any other qualified professional. We make no representations, warranties, or guarantees, whether express or implied, that the content in this publication is accurate, complete, or up to date.