
 0800 855 888
Your Easy Guide to Getting Loans: Steps for Financial Success
Introduction
Grasping the nuances of personal loans can truly transform your approach to financial management. This guide not only clarifies the different uses of personal loans – from consolidating debt to funding education – but also provides you with essential strategies for evaluating your financial situation and effectively comparing loan options. With so many choices at your fingertips, how can you ensure that you’re making the best decision for your unique needs?
As you explore the steps necessary to secure loans that align with your financial goals, remember that every step counts! By understanding the features of various lending options, you can appreciate their advantages and the benefits they bring to your financial health. This journey toward a more secure financial future is within your reach, and with the right information, you can take control of your finances!
Understand Personal Loans and Their Uses
Personal credit options are unsecured financial products that empower individuals to borrow a specific amount for various purposes, such as home improvements, debt consolidation, and unexpected expenses. With fixed repayment terms and interest rates, they provide flexibility and predictability for borrowers. Here are some prevalent uses for personal loans:
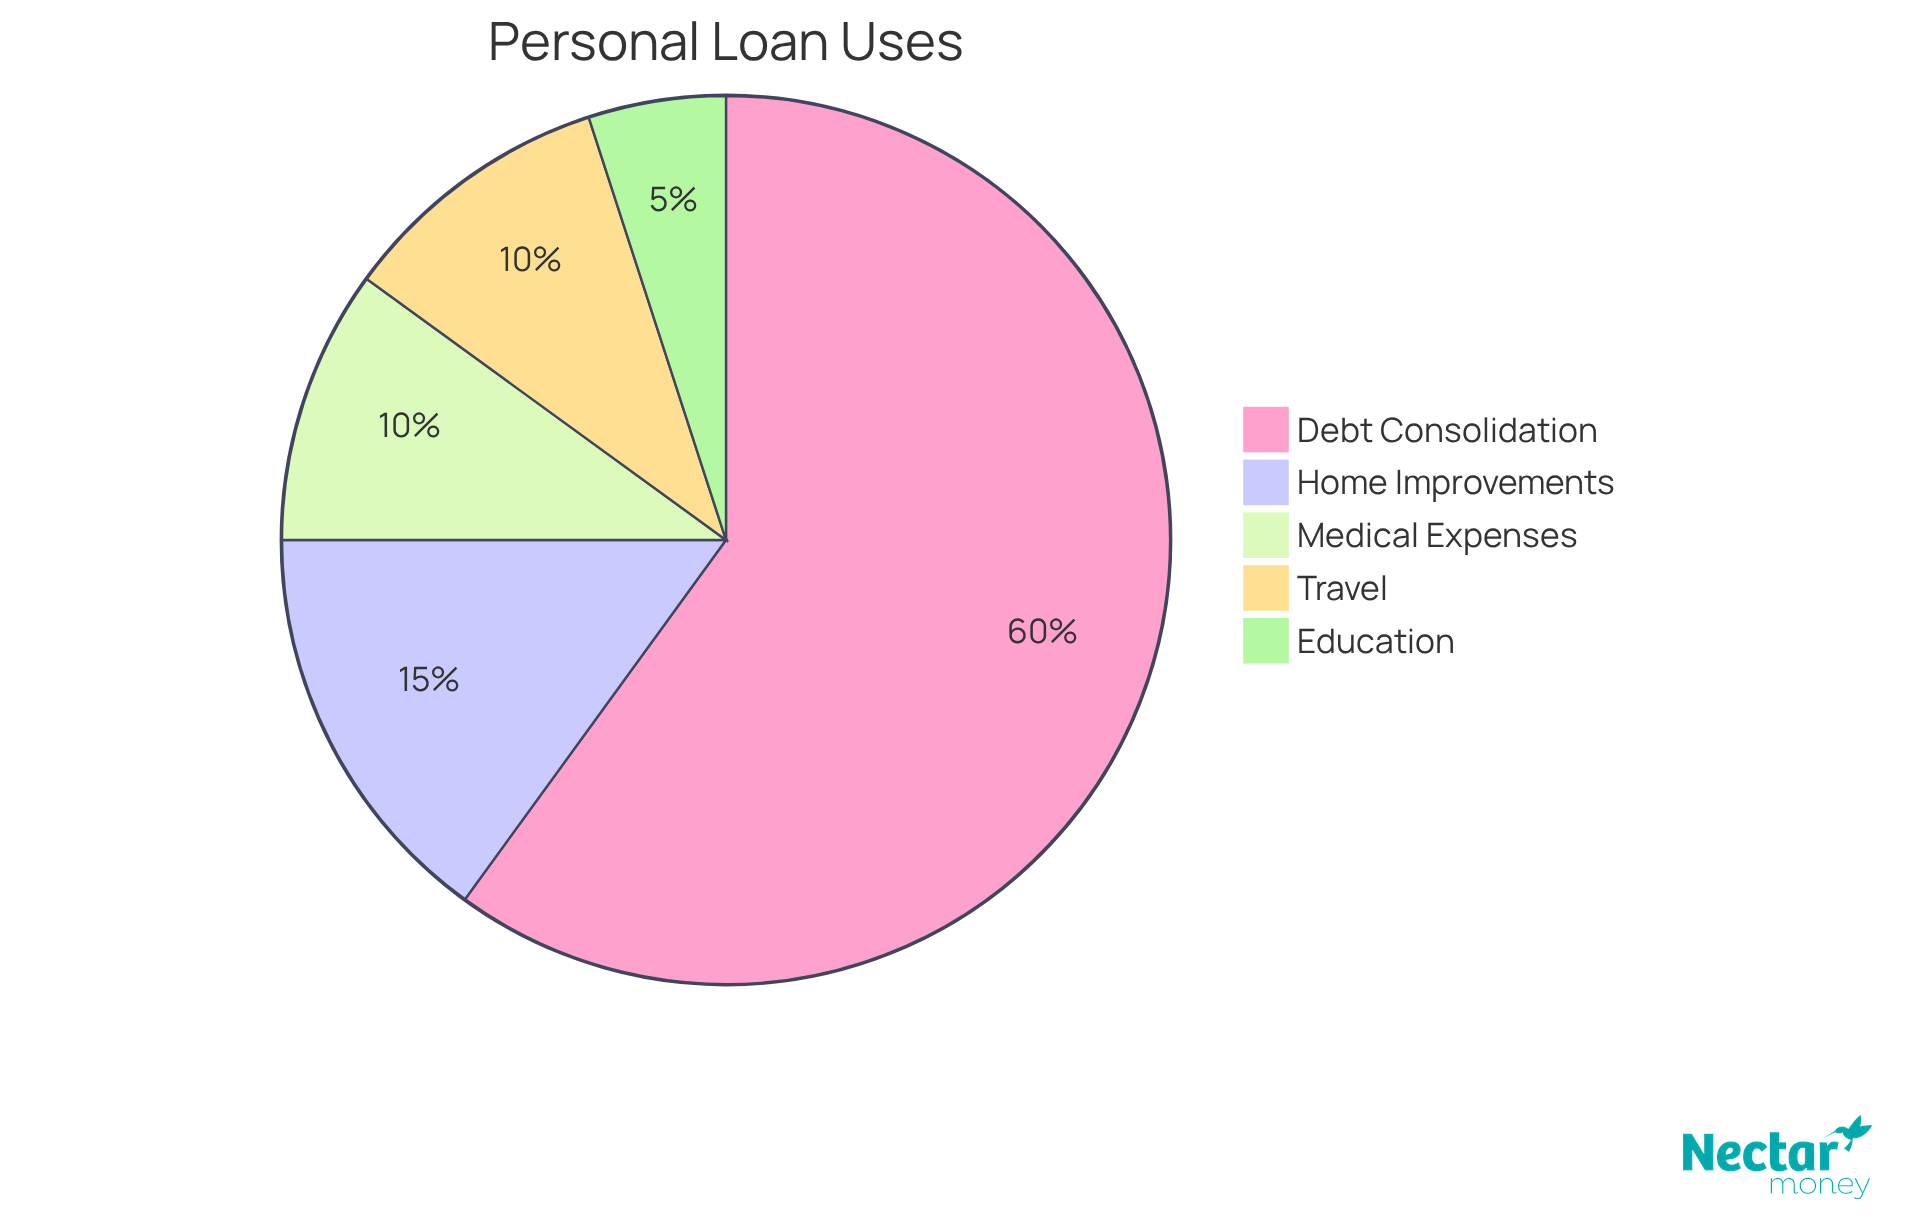
- Debt consolidation: Many borrowers take advantage of personal loans to consolidate multiple debts into a single loan, often benefiting from a lower interest rate. Recent data indicates that around 60% of individual credit options in New Zealand are used for this purpose, showcasing a growing trend among households striving to manage their finances more effectively. You can take control of your finances by consolidating your debts!
- Home improvement: Personal financing can also support renovations or repairs, enhancing the value of a home. For instance, homeowners may borrow to upgrade kitchens or bathrooms, which can yield significant returns on investment. Financial advisors recommend this approach, noting that well-planned improvements can increase property value and appeal. Every step counts when it comes to boosting your home’s worth!
- Medical expenses: Unexpected medical bills can arise at any moment, and individual financing offers a way to cover these costs. With the right steps, you can ensure that you’re prepared for the unexpected.
- Travel: Funding a holiday or vacation through a private credit option allows individuals to enjoy experiences without the burden of upfront cash payments. This option is especially appealing during peak travel seasons when costs can soar. Imagine creating lasting memories without financial stress!
- Education: Personal loans can help finance education, making higher education more accessible. Investing in your education is a powerful step towards a brighter future.
Understanding these applications helps individuals evaluate whether a private credit option aligns with their financial goals. As the demand for individual credit options, especially personal loans, continues to rise amid increasing living expenses, they remain a practical choice for many Kiwis looking to navigate their economic landscape. Remember, taking informed steps today can lead to a more secure financial tomorrow!
Assess Your Financial Situation
Before you request an individual credit option, it’s crucial to evaluate your financial situation. Here’s how you can effectively assess your finances:
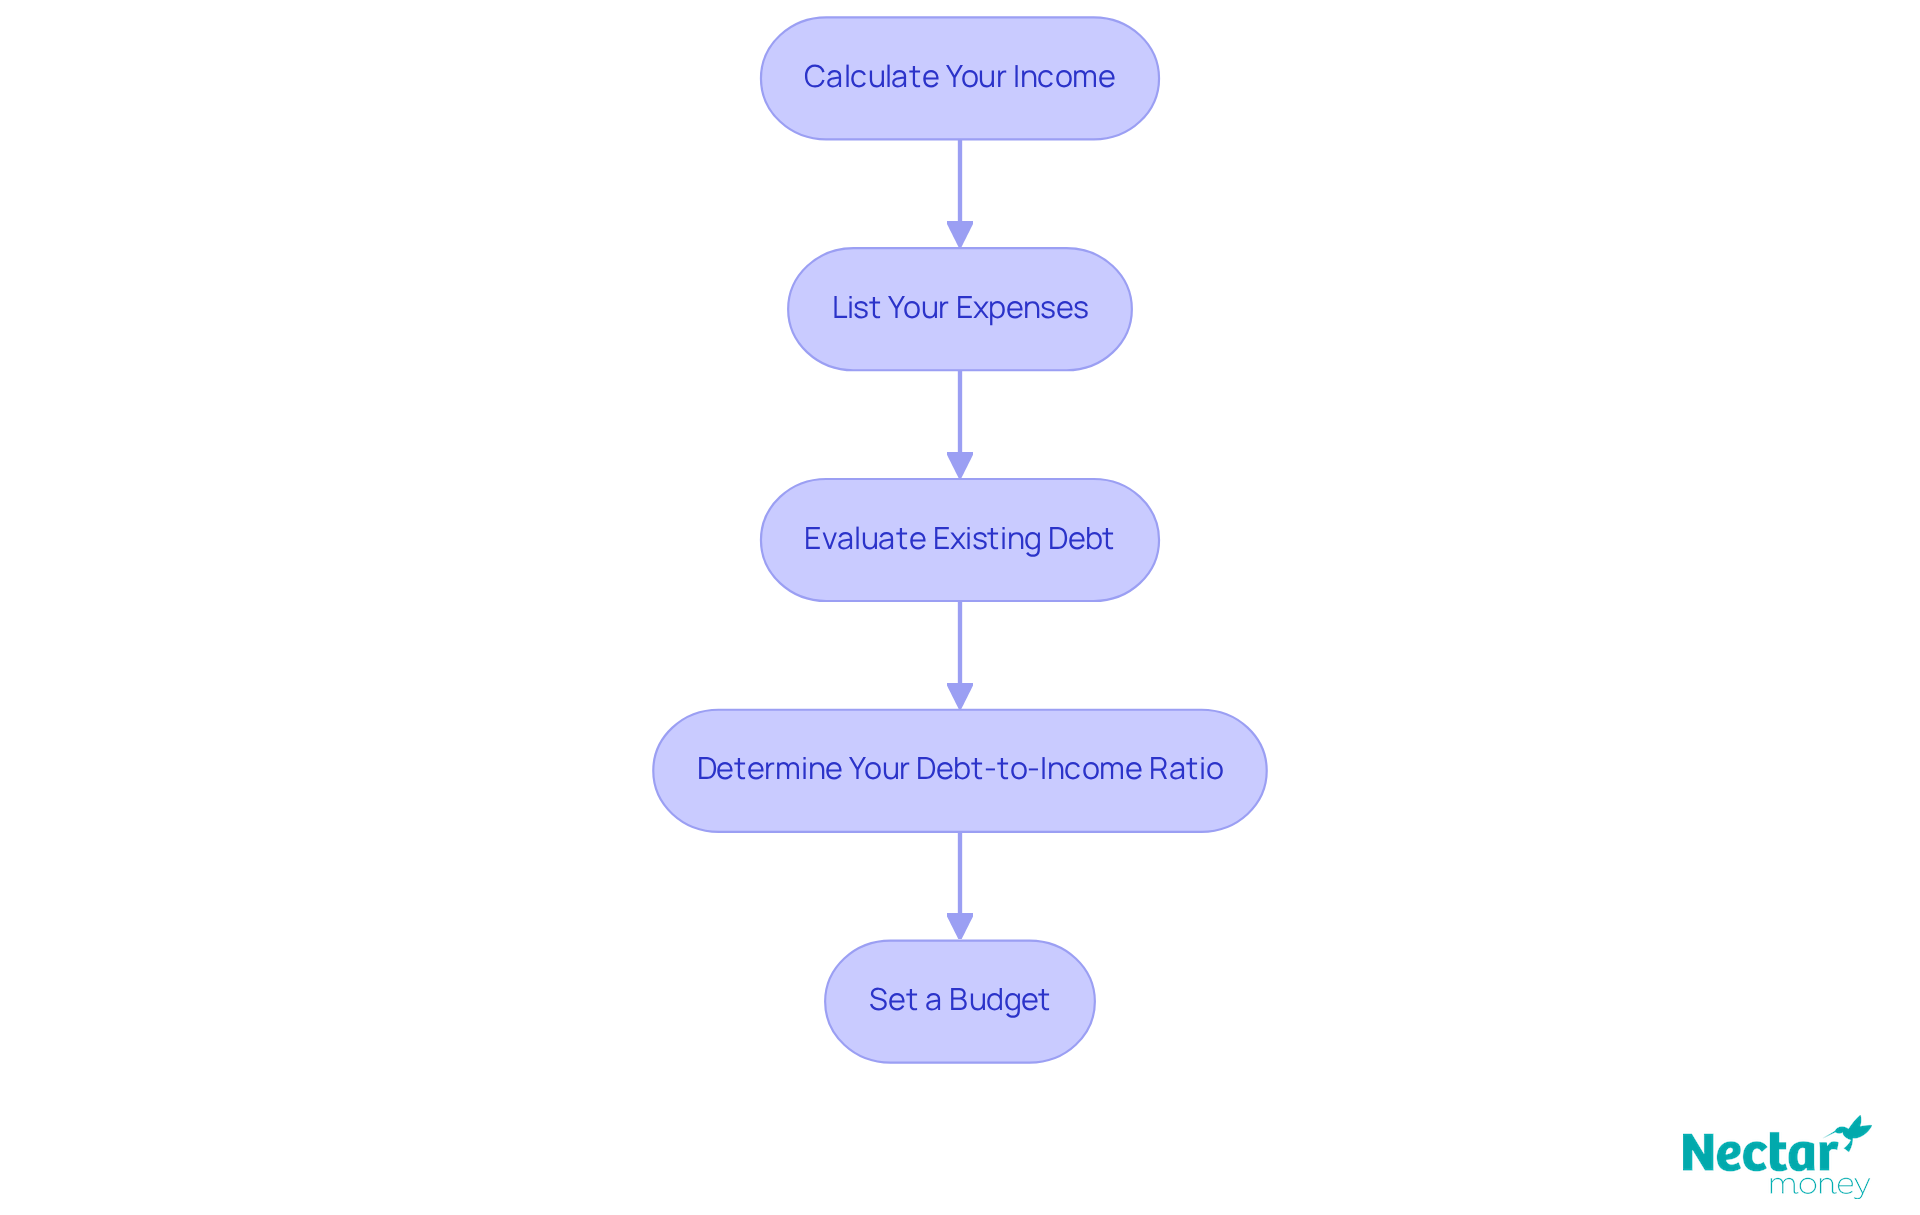
- Begin by determining your total monthly income, which includes your salary, bonuses, and any additional sources of income. Knowing your income is the first step toward financial clarity.
- Track your monthly expenses, including rent or mortgage, utilities, groceries, and discretionary spending. This will give you a clear view of your expenses and help you understand where your money goes.
- Take stock of any current debts, such as credit cards, student loans, or personal borrowing. Understanding your debts is essential for determining how much you can borrow responsibly.
- Calculate your debt-to-income ratio by dividing your total monthly debt payments by your gross monthly income. A lower DTI ratio indicates better financial health and increases your chances of approval. For example, if you have total debts of $500,000 and a gross annual income of $100,000, your DTI ratio would be 5, which might raise concerns for lenders.
- Create a budget that outlines how much you can allocate toward debt repayments without compromising essential expenses. This structured approach not only helps you manage your finances but also prepares you for responsible borrowing.
By thoroughly understanding your financial situation, you can make informed choices about the amount and terms that will make it easy to get loans that best suit your needs. Remember, every step counts! Taking control of your finances now can enhance your chances of obtaining favourable borrowing conditions.
Research and Compare Loan Options
Once you’ve evaluated your financial condition, the next step is to research and compare borrowing options. Here’s how you can take control of your finances:
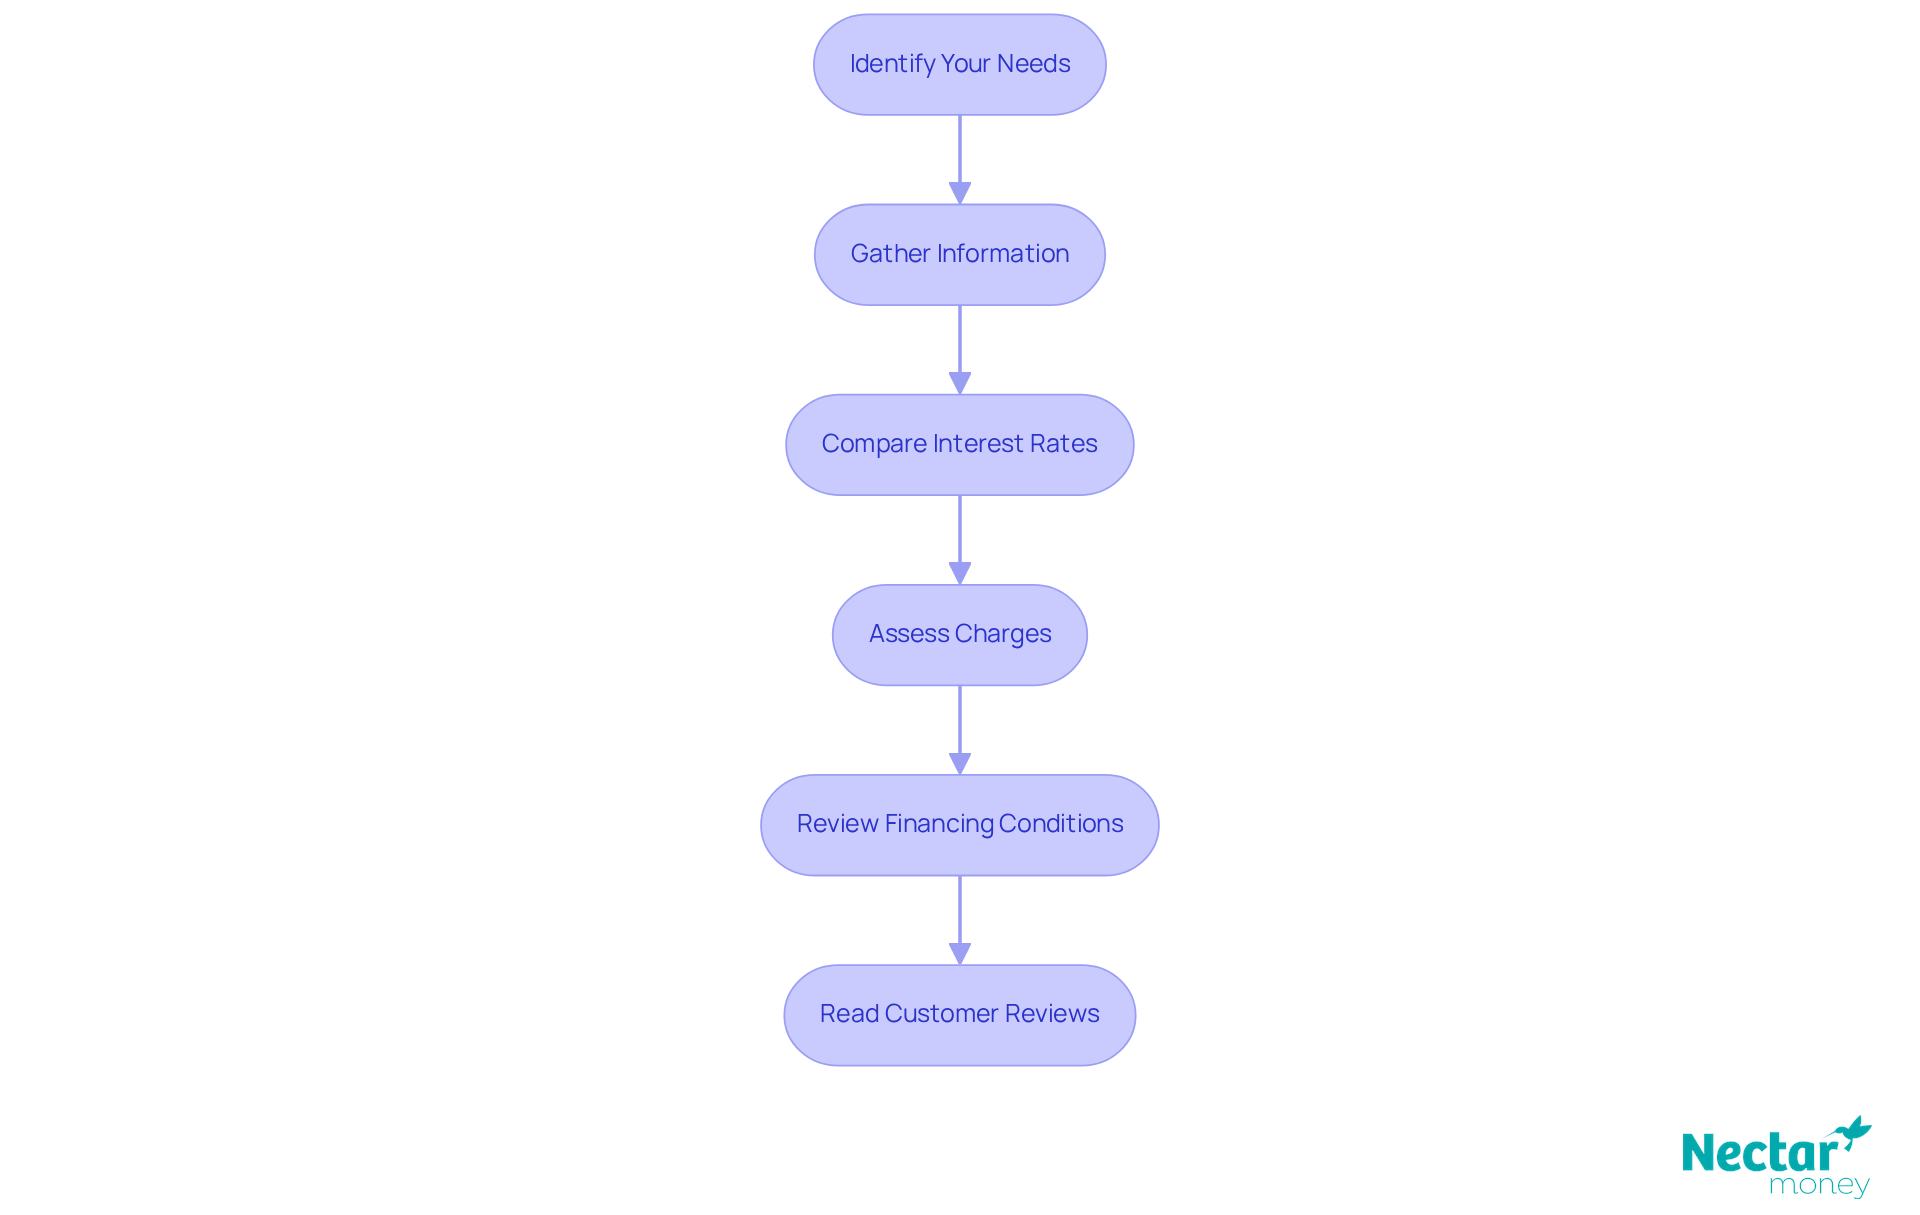
- Identify Your Needs: Start by determining the amount you need to borrow and the purpose of the funds. Whether it’s for personal expenses, vehicle purchases, or home improvements, knowing your needs is crucial to help cover major expenses, consolidate debt, or manage unexpected costs.
- Gather Information: Explore financing options from various lenders, including Nectar Money. Collect details about their offerings, such as interest rates. With Nectar Money, you can also look into specific loan types or home enhancements, ensuring you find what suits you best.
- Compare Interest Rates: As you consider your options, keep in mind that interest rates can vary significantly. For example, some lenders may offer lower rates, while other lenders may have competitive rates, such as the new rates effective from December 9, 2025, which include 5.79% p.a. for the special variable rate, 6.59% p.a. for the standard variable rate, and 5.89% p.a. for the revolving credit rate. It’s essential to check the latest rates to secure the best deal for your financial health.
- Assess Charges: Don’t forget to consider any extra charges linked to borrowing, like a processing fee or an administrative fee of $1.75 per payment. Understanding these costs will help you evaluate the overall expenditure of the borrowing, ensuring you make informed choices.
- Review Financing Conditions: Take a close look at the payment terms, including the duration of the financing, which can range from 6 months to 5 years, and any penalties for early settlement. Nectar Money, for instance, does not impose early repayment fees, providing you with flexibility. This flexibility is reflected in customer testimonials, where borrowers share their positive experiences.
- Read Customer Reviews: Look for feedback from other borrowers to gauge the lender’s reputation and customer service. Positive reviews can indicate a lender’s reliability and responsiveness. Clients have praised Nectar Money for quick approvals and outstanding service, highlighting how the company has helped them manage monetary emergencies effortlessly.
As Finance Minister Nicola Willis emphasizes, “Don’t just look at the headline rates; go and hold your bank’s feet to the fire. See if another bank will give you a better rate.” By thoroughly researching and comparing financing options, you can select the best choice among the easy to get loans that aligns with your financial goals. Remember, every step counts towards making an informed decision!
Complete the Loan Application Process
Finalizing the application is a crucial step toward securing your financing. Here’s a streamlined guide to help you navigate this phase effectively:
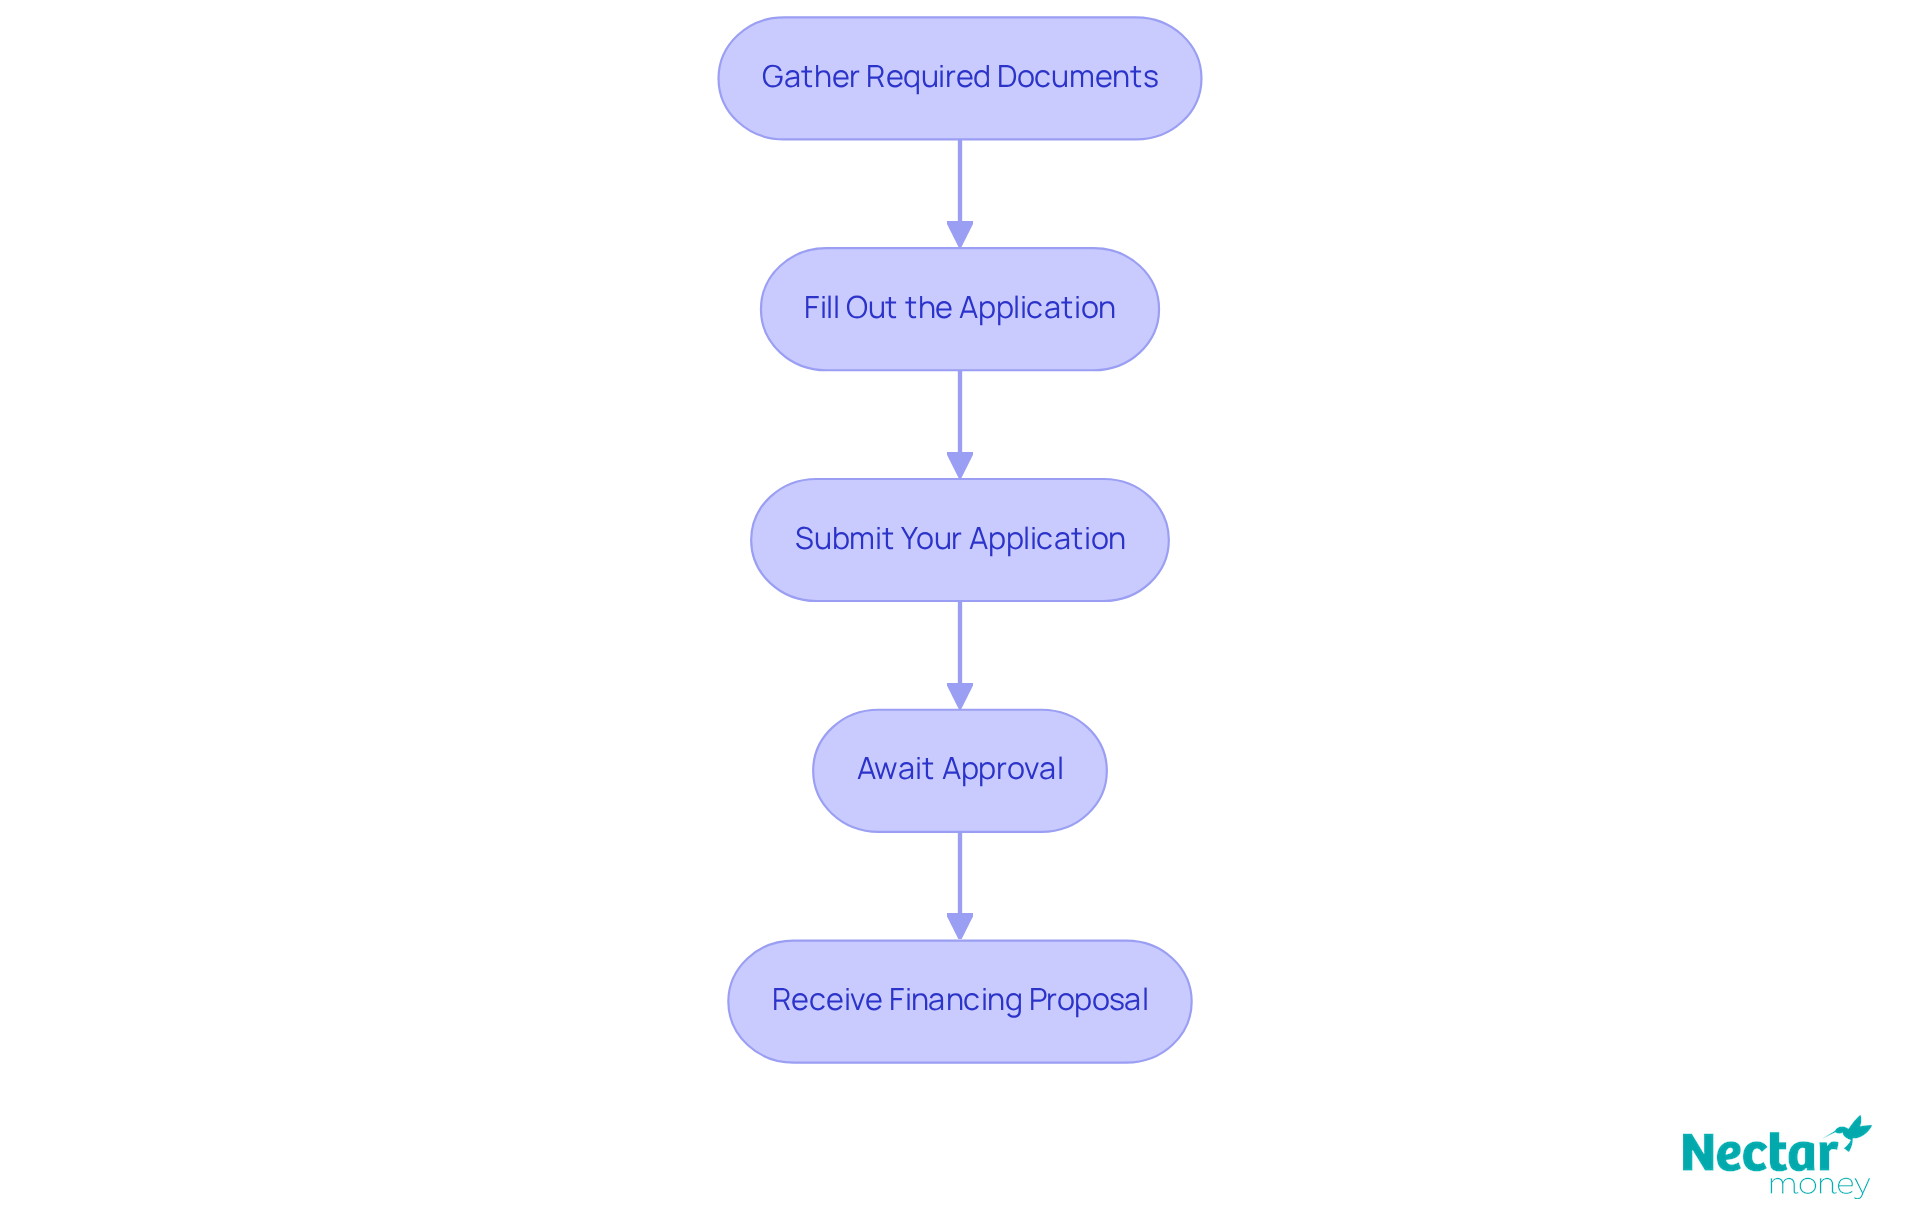
- Gather Required Documents: Start by collecting items like identification (e.g., driver’s licence or passport), income verification (such as recent payslips or tax returns), and a comprehensive overview of your expenses and debts. In 2025, the most common documents needed for loans in New Zealand include bank statements and proof of residence. By having these ready, you can take control of your finances!
- Fill Out the Application: Carefully complete the application form, ensuring that all information is accurate and thorough. Avoid omitting details or providing inconsistent information, which can delay the approval process. Remember, every detail counts!
- Submit Your Application: Depending on the lender’s process, you can apply online or in person. Online applications have become increasingly popular, with many borrowers opting for this method in 2025 due to its convenience. With the right steps, you can make this process smoother!
- Await Approval: After submission, the lender will review your application. Be prepared for potential follow-up questions, as lenders may require additional information to finalise their decision. Stay positive; this is a normal part of the process!
- Receive Offer: If your application is approved, you will receive a document outlining the terms and conditions. Take the time to review it to ensure it meets your needs. This is your opportunity to secure the best deal for your loan!
By following these steps, you can facilitate a smoother application process and significantly enhance your chances of obtaining the financing you need. Remember, every step counts on your journey to financial success!
Review Loan Terms and Conditions
Before you accept an offer from Nectar Money, it’s essential to review the terms and conditions carefully. Here’s what you should focus on:
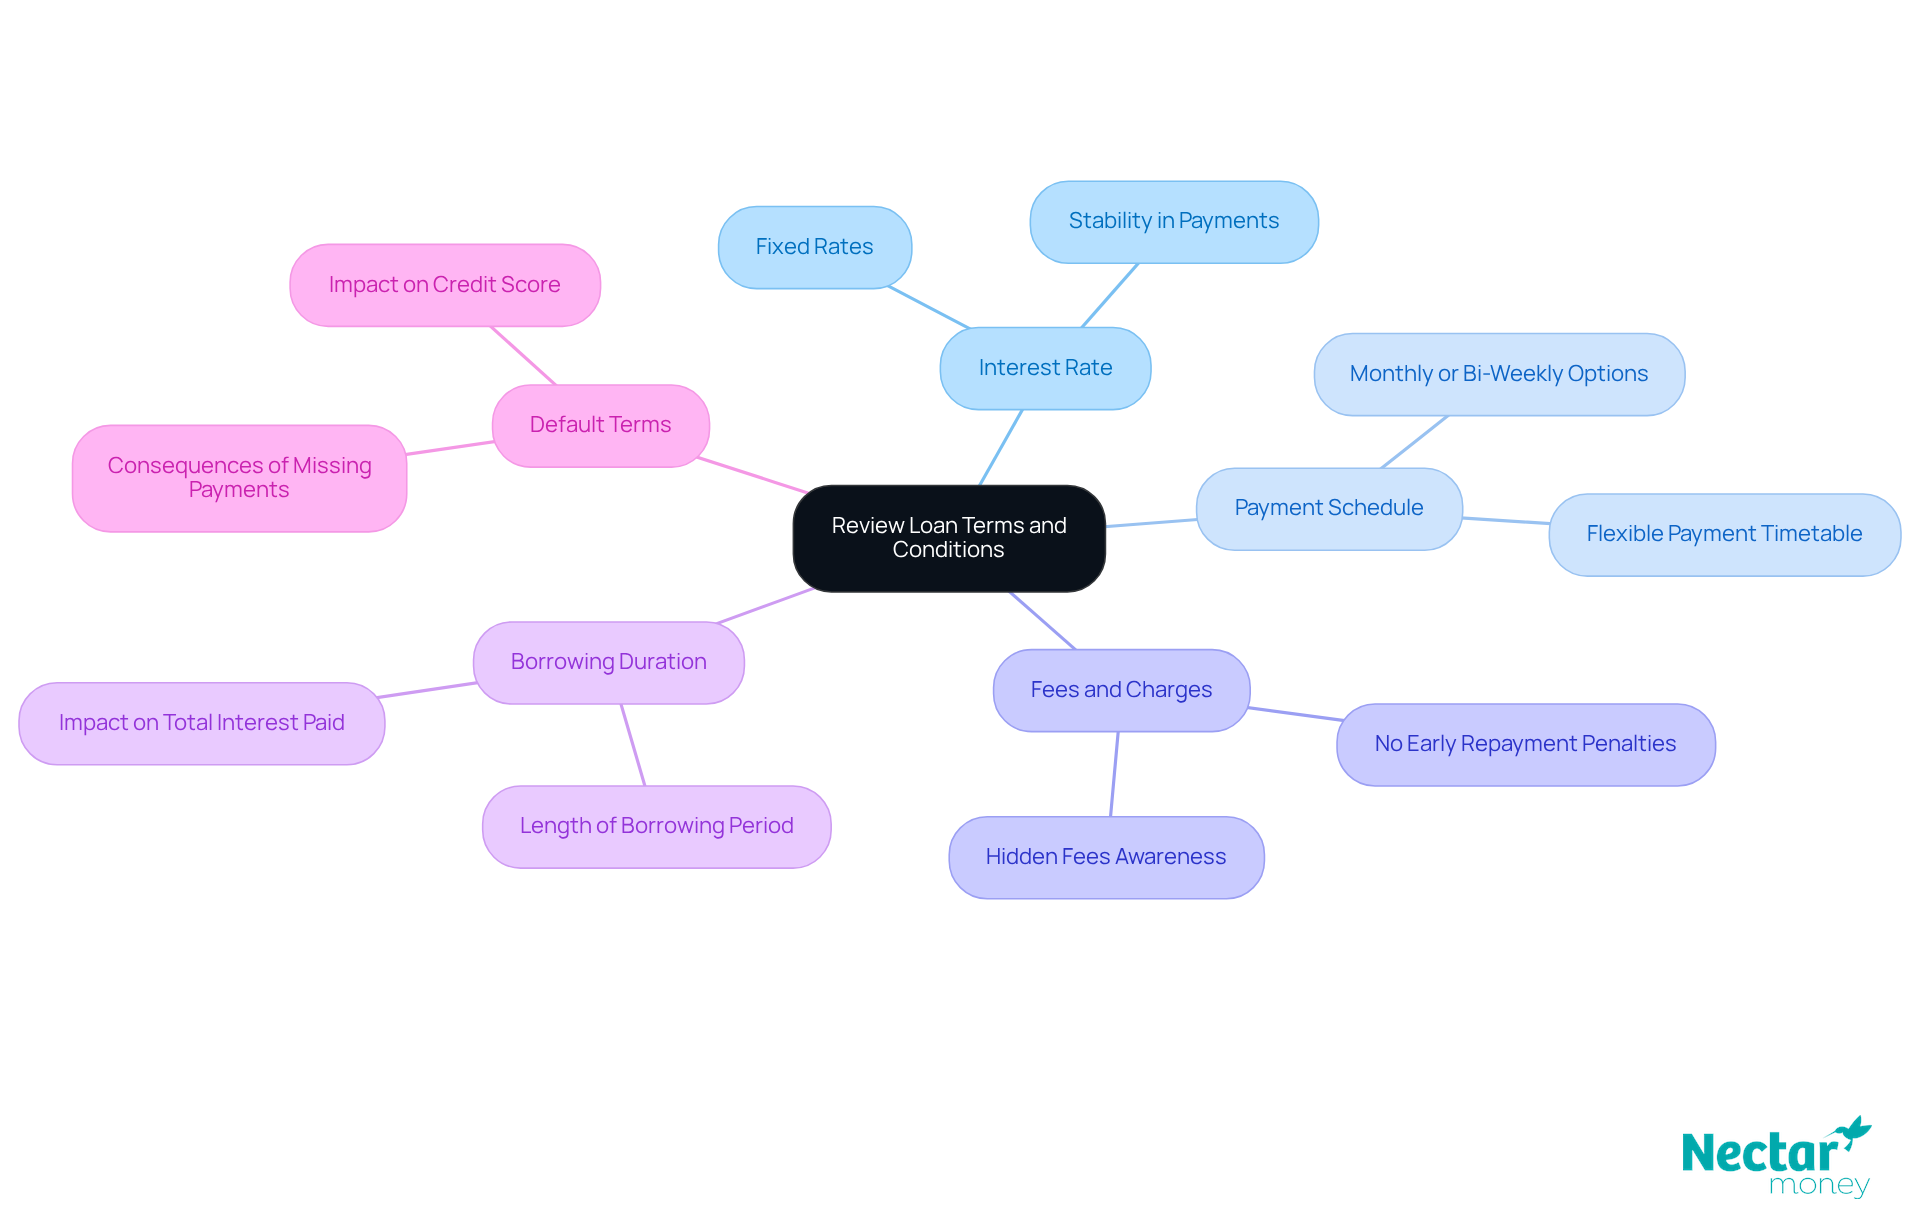
- Interest Rate: Make sure you understand whether the rate is fixed. Nectar Money provides a fixed rate for the duration of the loan, making it easy to get loans while ensuring stability in your payments. This can be a great advantage as it helps you plan your finances better.
- Payment Schedule: Check the schedule whether it’s monthly or bi-weekly and ensure it aligns with your budget. Nectar Money provides options, making it easy to get loans by allowing you to choose a timetable that fits your financial situation. You can take control of your finances!
- Fees and Charges: Be on the lookout for any fees, such as late payment charges or early payoff penalties. With Nectar Money, there are no hidden fees, which can be beneficial if you decide to pay off your debt sooner. Every step counts towards your financial success!
- Borrowing Duration: Verify the length of the loan and how it impacts the total cost. Understanding this duration will help you gauge the overall cost of borrowing, empowering you to make informed decisions.
- Default Terms: Familiarise yourself with the consequences of missing payments and how it may affect your credit score. Knowing these terms can assist you in managing your credit responsibly, ensuring you stay on track.
Additionally, consider using Nectar Money’s calculator to estimate your payments based on different amounts and terms. By thoroughly reviewing these terms, you can make an informed decision and avoid any surprises down the line. Remember, with the right steps, you can achieve your financial goals!
Manage Your Loan Repayments Effectively
Once you obtain a private credit, effective oversight of your payments is crucial for sustaining your financial health. You can take control of your finances by implementing these key strategies:
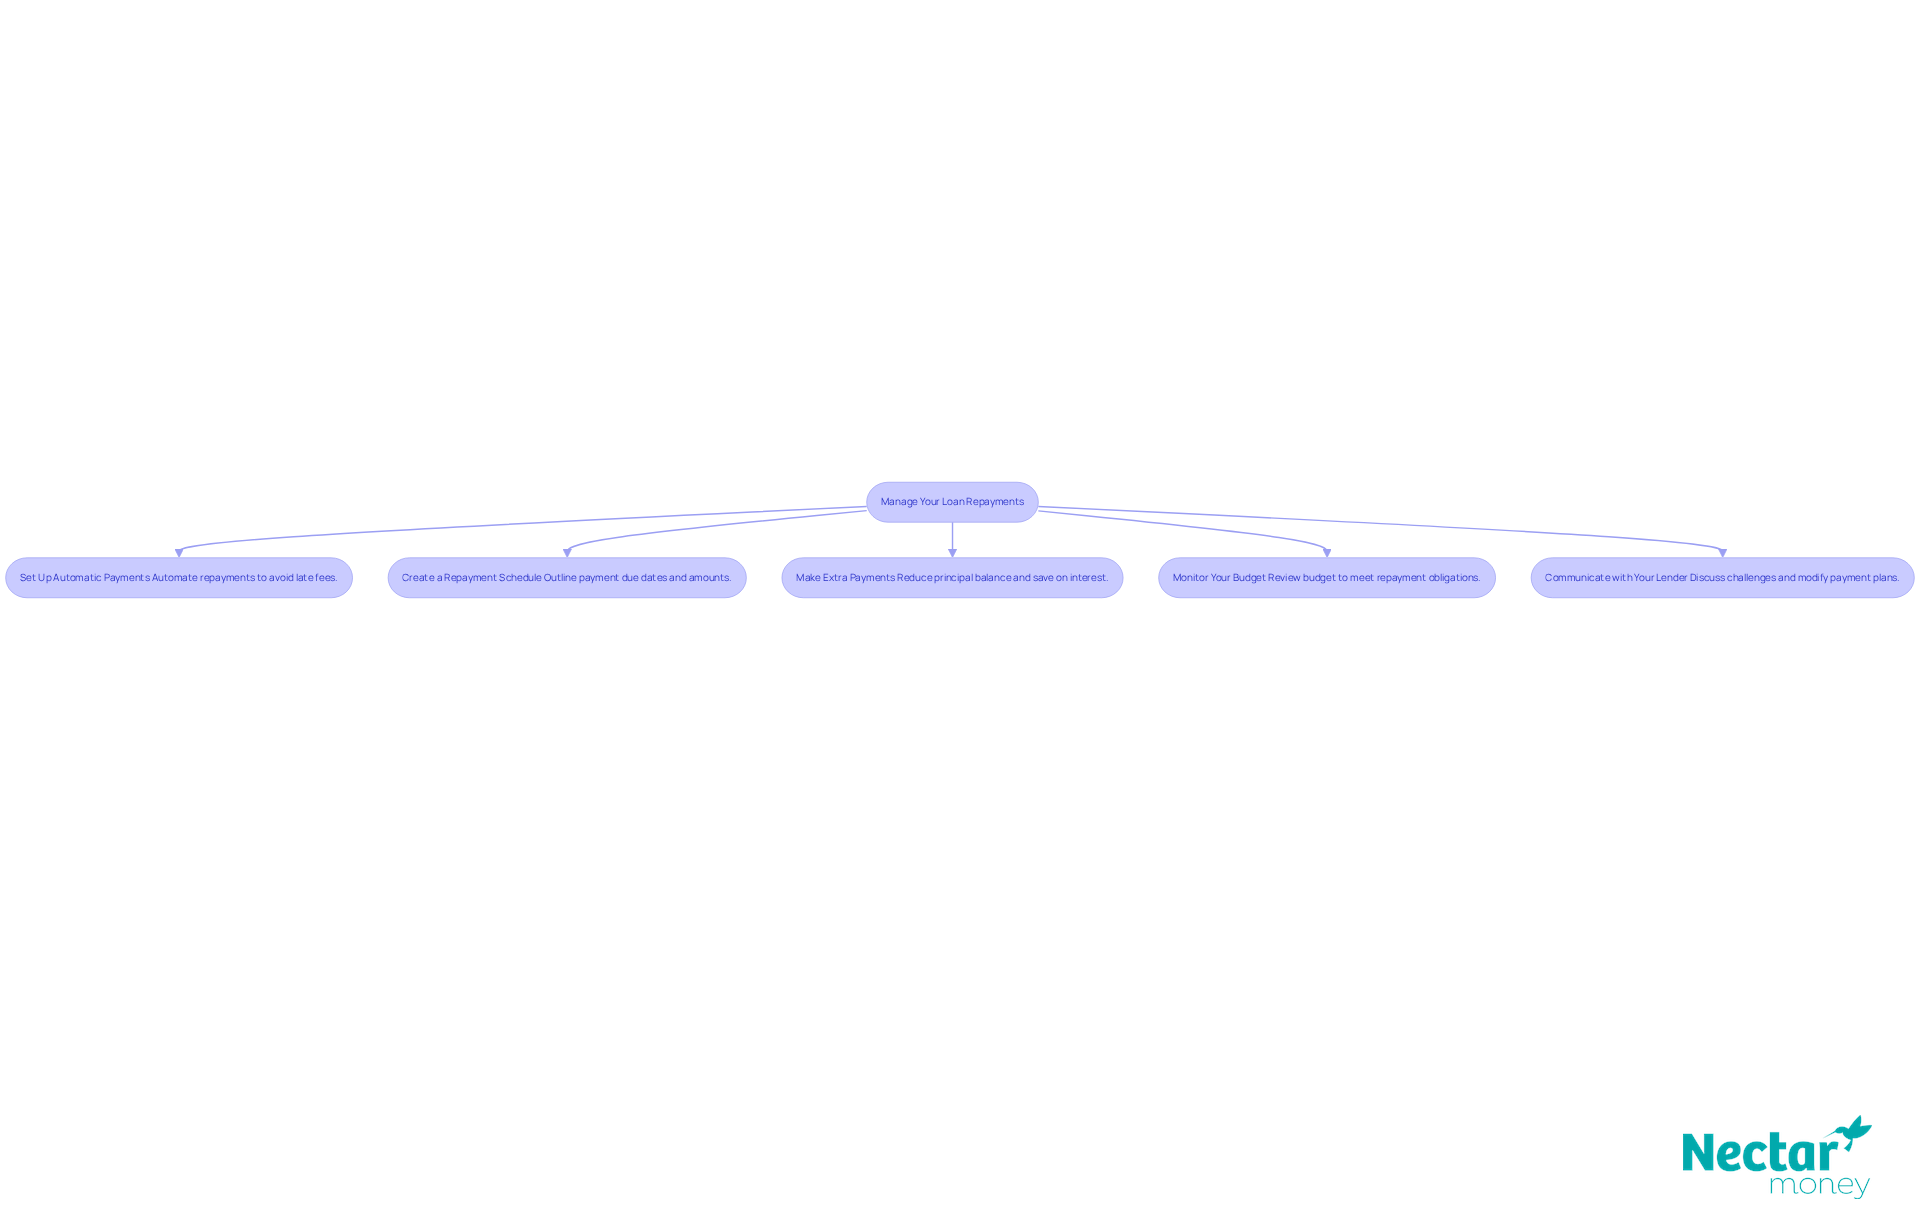
- Set Up Automatic Payments: Automating your repayments ensures they are made on time, significantly reducing the risk of late fees. In 2025, statistics indicate that late payment rates for personal credit in New Zealand remain a concern, making automation a wise option for borrowers. By setting this up, you can enjoy peace of mind knowing your payments are handled.
- Create a Payment Schedule: Develop a clear schedule that outlines payment due dates and amounts. This clarity helps you stay organised and prepared for upcoming obligations. With a solid plan in place, you can approach your payments with confidence.
- Make Extra Payments: Whenever possible, consider making additional payments to reduce your principal balance. This strategy not only shortens the term of the credit but also saves on interest expenses over time. Every extra payment counts towards your financial freedom!
- Review Your Budget: Regularly review your budget to ensure you can comfortably meet your loan obligations. Adjusting your budget to accommodate loan payments is essential for economic stability. Staying on top of your finances empowers you to make informed decisions.
- Communicate with Your Lender: If you encounter monetary challenges, proactively contact your lender. Open communication can lead to options for altering your payment plan, ensuring you stay on track. Remember, your lender is there to help you navigate any difficulties.
Monetary coaches highlight that establishing a repayment plan can result in enhanced money management, as it streamlines the payment process and aids in preventing missed transactions. Numerous borrowers have effectively employed these strategies to uphold their financial commitments, demonstrating its efficiency in promoting fiscal discipline. By implementing these strategies, you can effectively manage your loan repayments and enhance your overall financial well-being. Every step you take brings you closer to your financial goals!
Conclusion
Understanding personal loans and their various applications is crucial for anyone eager to navigate their financial landscape effectively. By recognising how these loans can serve purposes like debt consolidation, home improvements, and unexpected expenses, you can make informed decisions that align with your financial goals.
This article highlights essential steps for obtaining a personal loan:
- Assess your financial situation
- Research and compare loan options
- Complete the application process
- Review loan terms
It’s vital to understand your income, expenses, and existing debts. Thorough research will help you find the best loan options available. Moreover, managing loan repayments effectively is key to achieving long-term financial stability.
Ultimately, taking proactive steps in the loan process can lead to greater financial success. By carefully evaluating your needs, comparing options, and managing repayments, you can ensure that you’re making sound financial decisions. Embracing these practises not only fosters financial literacy but also empowers you to take control of your financial future, paving the way for a more secure and prosperous tomorrow. Remember, every step counts, and with the right actions, you can take control of your finances!
Frequently Asked Questions
What are personal loans and their typical uses?
Personal loans are unsecured financial products that allow individuals to borrow a specific amount for various purposes, such as debt consolidation, home improvements, medical expenses, travel, and education.
How can personal loans help with debt consolidation?
Personal loans can consolidate multiple debts into a single loan, often at a lower interest rate. In New Zealand, around 60% of personal loans are used for this purpose, helping borrowers manage their finances more effectively.
In what ways can personal loans be used for home improvements?
Personal loans can finance renovations or repairs to a home, such as upgrading kitchens or bathrooms, which can enhance the property’s value and appeal.
How do personal loans assist with unexpected medical expenses?
Personal loans provide a way to cover unexpected medical bills without depleting savings, allowing individuals to manage healthcare costs more effectively.
Can personal loans be used for travel expenses?
Yes, personal loans can fund holidays or vacations, enabling individuals to enjoy experiences without the burden of upfront cash payments, especially during peak travel seasons.
How can personal loans help with education costs?
Personal loans can assist with tuition and other educational expenses, making higher education more accessible for individuals looking to invest in their future.
What steps should I take to assess my financial situation before applying for a personal loan?
You should calculate your total monthly income, list your monthly expenses, evaluate existing debt, determine your debt-to-income ratio, and set a budget for debt repayments.
Why is it important to evaluate my debt-to-income ratio?
A lower debt-to-income (DTI) ratio indicates better financial health and increases your chances of credit approval. It helps lenders assess your ability to manage additional borrowing.
What is the benefit of setting a budget before applying for a personal loan?
Creating a budget helps you understand how much you can allocate toward debt repayments without compromising essential expenses, preparing you for responsible borrowing.
List of Sources
- Understand Personal Loans and Their Uses
- Company liquidations up 26% despite improving credit trends (https://rnz.co.nz/news/top/574630/company-liquidations-up-26-percent-despite-improving-credit-trends)
- Loansmart – The Average Size Of Debt Consolidation Loans Increased By $5,000 (https://scoop.co.nz/stories/BU2301/S00189/loansmart-the-average-size-of-debt-consolidation-loans-increased-by-5000.htm)
- Personal Loans In High Demand >> Loansmart (https://loansmart.co.nz/in-new-zealand-personal-loans-are-in-high-demand)
- Westpac offers special debt consolidation loan as survey shows new year financial stress. (https://westpac.co.nz/about-us/media/westpac-offers-special-debt-consolidation-loan-as-survey-shows-new-year-financial-stress)
- Assess Your Financial Situation
- harcourts.net (https://harcourts.net/nz/resources/residential/how-to-boost-your-chances-of-home-loan-approval-in-2025)
- Read our latest article about Debt-to-income ratios. | Rapson Loans & Finance (https://rapson.co.nz/debt-to-income-ratios)
- New Debt-To-Income Ratios: What You Need To Know – Mortgage Suite mortgage brokers Auckland, New Zealand (https://mortgagesuite.co.nz/new-debt-to-income-ratios-what-you-need-to-know-mortgage-suite)
- Understanding Personal Loans: What to Know Before You Apply (https://info.better.co.nz/news/understanding-personal-loans-what-to-know-before-you-apply)
- What Banks Look for When Approving Your Home Loan — LookAhead (https://lookahead.co.nz/blog/what-banks-look-for-when-approving-your-home-loan)
- Research and Compare Loan Options
- More major banks lift some fixed mortgage rates (https://1news.co.nz/2025/12/18/more-major-banks-lift-some-fixed-mortgage-rates)
- Lending rate changes – 2 December 2025 (https://tsb.co.nz/about/news/lending-rate-changes-2-december-2025)
- Nicola Willis urges mortgage holders to ‘shop around’ (https://1news.co.nz/2025/12/11/nicola-willis-urges-mortgage-holders-to-shop-around)
- Complete the Loan Application Process
- Why Getting Home Loan Approval Early Matters More Than Ever (https://scoop.co.nz/stories/BU2511/S00463/why-getting-home-loan-approval-early-matters-more-than-ever.htm)
- Why home loan applicants might face an extra wait (https://rnz.co.nz/news/business/582534/why-home-loan-applicants-might-face-an-extra-wait)
- The Loan Process Explained: How an Adviser Can Help (https://rwwhangarei.co.nz/news/loans-how-a-mortgage-adviser-can-help)
- mortgagelink.co.nz (https://mortgagelink.co.nz/about/news/from-application-to-keys-mortgage-process)
- harcourts.net (https://harcourts.net/nz/resources/residential/how-to-boost-your-chances-of-home-loan-approval-in-2025)
- Review Loan Terms and Conditions
- Loan Direct Urges Borrowers To Review Existing Loans As Cost Pressures Peak Ahead Of Christmas (https://scoop.co.nz/stories/BU2510/S00184/loan-direct-urges-borrowers-to-review-existing-loans-as-cost-pressures-peak-ahead-of-christmas.htm)
- Understanding Home Loans Interest Rates NZ: Key Insights for Borrowers – Nectar Money (https://nectar.co.nz/understanding-home-loans-interest-rates-nz-key-insights-for-borrowers)
- opespartners.co.nz (https://opespartners.co.nz/mortgage/interest-rates)
- canstar.co.nz (https://canstar.co.nz/home-loans/lowest-mortgage-rates-new-zealand)
- Manage Your Loan Repayments Effectively
- Managing Loan Repayments: Strategies for Staying on Track (https://info.better.co.nz/news/managing-loan-repayments-strategies-for-staying-on-track)
- 3 Smart Tips for Effective Loan Management (https://loanspot.co.nz/news/3-tips-for-smart-loan-management)
- News: Strategies to kickstart a financial reset in 2025 – Moneysmart.gov.au (https://moneysmart.gov.au/media-centre/news-strategies-to-kickstart-a-financial-reset-in-2025)
- Effective Debt Management Strategies: Take Control of Your Finances | Instant Finance (https://instantfinance.co.nz/our-blogs/effective-debt-management-strategies)
- 10 Smart Strategies for Effective Personal Loan Repayments – Nectar Money (https://nectar.co.nz/10-smart-strategies-for-effective-personal-loan-repayments)
* Nectar Money offers competitive unsecured personal loan rates with fixed interest rates from 7.95% to 29.95% p.a., based on your credit profile. A $240 establishment fee and $1.75 administration fee per repayment apply. Strong Credit borrowers may qualify for low, competitive rates from 7.95% to 11.95% p.a.; Good Credit borrowers may qualify for rates from 14.95% to 22.95% p.a.; and Fair or Developing Credit borrowers may qualify for rates from 24.95% to 29.95% p.a. The broad range helps Nectar offer low interest rates to borrowers with excellent credit, while also providing loan options for more New Zealanders, including borrowers with fair or developing credit profiles. Learn more here.
All loans are subject to responsible lending checks and standard borrowing criteria. Please see our privacy policy and rates and terms, or visit our FAQs for the most up to date information. This publication is provided for general information purposes only and does not constitute legal, tax, financial, or other professional advice from Nectar Money. It is not intended as a substitute for obtaining advice from a financial adviser or any other qualified professional. We make no representations, warranties, or guarantees, whether express or implied, that the content in this publication is accurate, complete, or up to date.